Why Do Robotics Manufacturers Still Build Their Own Chips When They Account for 30% of Hardware Costs?
Why Do Robotics Manufacturers Still Build Their Own Chips When They Account for 30% of Hardware Costs?

2026-11-18 20:06
Introduction: NVIDIA’s Integrated Hardware-Software Ecosystem as a Blueprint—The Larger the Scale, the More Cost-Effective In-House Development Becomes. Domestic GPU vendors are now exploring new markets beyond data centers, with robotics emerging as a key frontier.
Domestic GPU vendors are actively seeking markets outside of data centers, and robotics stands out as one such promising direction. Recently, Shanghai Anxin Semiconductor Technology Co., Ltd. (hereinafter referred to as “Anxin Tech”) added Zhuhai Biren Integrated Circuit Co., Ltd. as a new shareholder.
Meanwhile, Ubtech disclosed that Xixuan Chuangzhi, jointly initiated by Ubtech and Muxi Semiconductor, successfully raised RMB 500 million in angel funding. Its first product is targeted at edge computing for robotics.
From investing in startups to forming joint ventures with system integrators, GPU vendors are adopting diverse strategies to enter the robotics market. At the same time, robotics companies are increasingly engaging in chip development at an earlier stage. The question remains: given the growing availability of off-the-shelf solutions, why invest in chip design? And what scale of production is required to justify such investment?
1. Former Employer Turns into Current Competitor?
Anxin Tech was founded in December 2025, focusing on physical AI applications. The company claims it plans to integrate its proprietary NPU architecture, edge inference models, and precision motion control technologies, with application areas extending to smart manufacturing and autonomous driving.
Following the latest business registration update, Zhuhai Biren holds approximately 2.81% equity in Anxin Tech. Taiya Capital, which previously invested in Muxi during its angel round, has also entered via its affiliated fund. Additionally, Anxin Tech’s shareholders include funds from Hillhouse Capital and iFlytek Capital, as well as Yankui Microelectronics (Suzhou) Co., Ltd.
The actual controller of Anxin Tech, Sun Erjun, personally holds over 20% equity. Prior to joining Muxi, he served in chip-related roles at Haier’s semiconductor platform, Canxin, Zensun Microelectronics, and Lanxin Technologies, where he held positions including product line manager and director of product and marketing.
In September 2020, he co-founded Muxi Semiconductor, serving as Vice President of Marketing and Chief Marketing Officer. Muxi focuses on general-purpose GPU and high-performance computing chip R&D. With the surge in domestic AI compute demand, Muxi listed on the STAR Market in December 2025. According to Muxi’s prospectus, Sun Erjun resigned in August 2024, and founded Anxin Tech more than a year later.
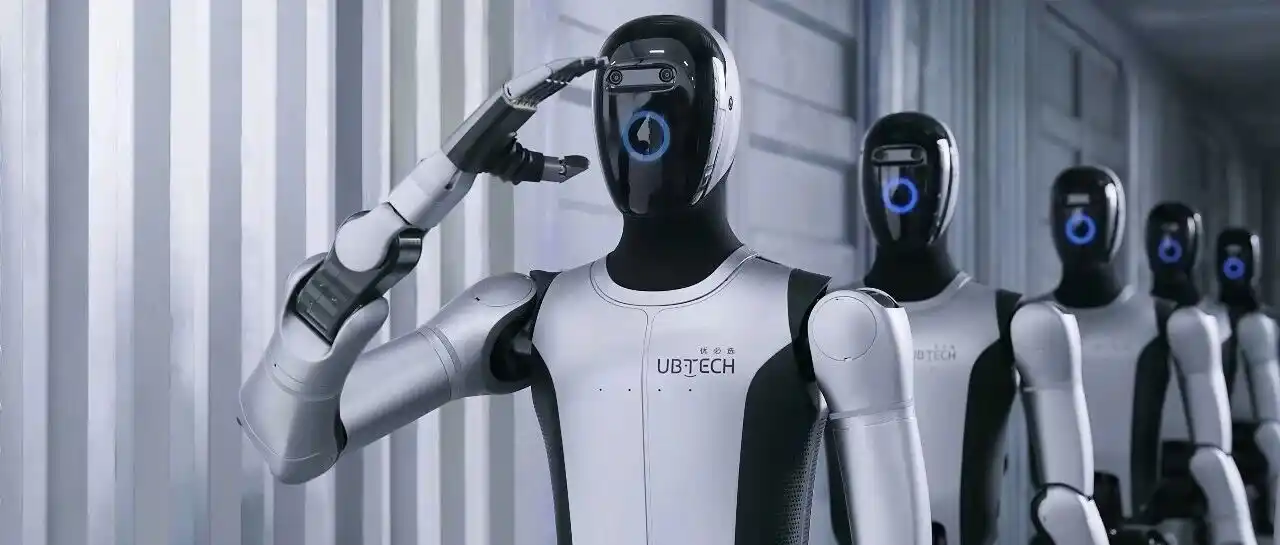
Five months after founding Anxin Tech, Sun Erjun’s former employer, Muxi, entered the same field, becoming a formidable competitor. Muxi co-initiated Xixuan Chuangzhi, positioning its first self-developed chip as a “brain-and-body integrated” SoC tailored for robotics—system-on-chip—directly targeting NVIDIA’s Thor chip. The plan includes launching a development validation platform by 2027 and mass-producing the SoC along with supporting solutions by 2028. The recently announced RMB 500 million angel round will be used for chip R&D, software toolchain development, and customer co-validation.
Other members of China’s “Four Greats” in GPU—Moore Threads and Tianshu Zhixin—have also launched edge computing modules aimed at robotics. Moore Threads’ MTT E300 features its proprietary “Changjiang” SoC, integrating CPU, GPU, and NPU, enabling integration by system OEMs for local perception and inference. Tianshu Zhixin has introduced modules like Tongyang TY1100 and disclosed collaboration with Glanro Robotics.
For GPU vendors, expanding from data center to edge robotics allows partial reuse of existing assets in compiler stacks, operator libraries, and model optimization. However, robotics imposes distinct requirements on power consumption, memory footprint, latency, and form factor, necessitating further adaptation of existing technologies. This enables GPU vendors not only to provide training and simulation compute for embodied intelligence firms but also to sell compute modules and deployment toolkits directly to them.
NVIDIA has already established this end-to-end ecosystem. Embodied intelligence companies can generate synthetic training data using the Cosmos world model, leverage tools like Isaac Sim and Isaac Lab for simulation and robot learning, use data center GPUs for model training, deploy Jetson platforms for edge inference, and apply TensorRT for inference optimization. For developers, using a unified software ecosystem reduces migration effort; switching platforms typically requires re-adapting models, performance tuning, and real-world validation.
Growing expectations for robot shipment volumes further justify GPU vendors’ move into edge compute. IDC’s September report increased its forecast for global humanoid robot annual shipments by ~50% to exceed 750,000 units by 2030. In the first half of 2026, global humanoid robot shipments reached nearly 25,000 units, up 432.1% year-over-year. As shipment volumes grow, the robot body itself may emerge as a new compute market for GPU vendors.
However, adding more chip products does not guarantee alignment with system-level needs. For robotics companies, choosing off-the-shelf chips, co-developing with suppliers, or establishing joint venture chip companies have become distinct strategic options.
2. Why Are Embodied Intelligence Firms Also Investing in Chips?
One key reason embodied intelligence firms are investing in chip development is cost. Ubtech Chairman Zhou Jian once remarked, “Overseas chips are too expensive—they account for one-third of hardware procurement costs.” Reducing this cost segment is one of the core motivations behind Ubtech’s joint chip R&D with Muxi. While switching to domestic chips incurs integration costs, embodied intelligence firms must weigh team familiarity with new toolchains and the additional manpower required for algorithm migration and robot debugging.
Given that purchasing chips involves significant costs and architectural transitions carry high switching expenses, participating in chip design tailored to specific product needs becomes a rational choice for embodied intelligence companies.
Embodied intelligence firm Galaxy General signed an agreement with automotive-grade chip vendor CEVA Technology in November 2025 to jointly develop next-generation robotic chips. According to the announcement, Galaxy General will bring multi-modal model and real-world robot application requirements into chip design, while CEVA provides expertise in chip R&D, mass production, and supply chain management.
Ubtech’s collaboration with Muxi reflects a similar strategy. Zhou Jian stated his desire to incorporate insights gained from robot R&D and application into early-stage chip design and validate products through real-world tasks.
The earlier chips are integrated into the R&D lifecycle, the greater the flexibility for adjustments before final product definition. Take Songyan Power and GigaDevice as examples—both parties began collaborating during the early chip selection phase for consumer-grade humanoid robot Bumi and continued through mass production.
When developing next-generation products, Songyan Power aims to achieve 21 degrees of freedom within a compact chassis and is evaluating GigaDevice’s new joint control chip. This chip integrates circuits needed to read motor position and speed, reducing peripheral components on the joint drive board. For engineering teams, the earlier they confirm how small the PCB can be, the more flexibility they have to adjust joint structure design.
This explains why the boundary between embodied intelligence firms and chip vendors is blurring. These firms understand exactly what tasks their customers expect robots to perform and are ultimately accountable for operational outcomes. The earlier they participate in chip R&D, the more effectively they can embed these requirements into chip design and validate whether the chip and robot meet expectations using real tasks before final product release.
Yet, involvement in chip development brings a new challenge: Is in-house chip R&D worth the investment?
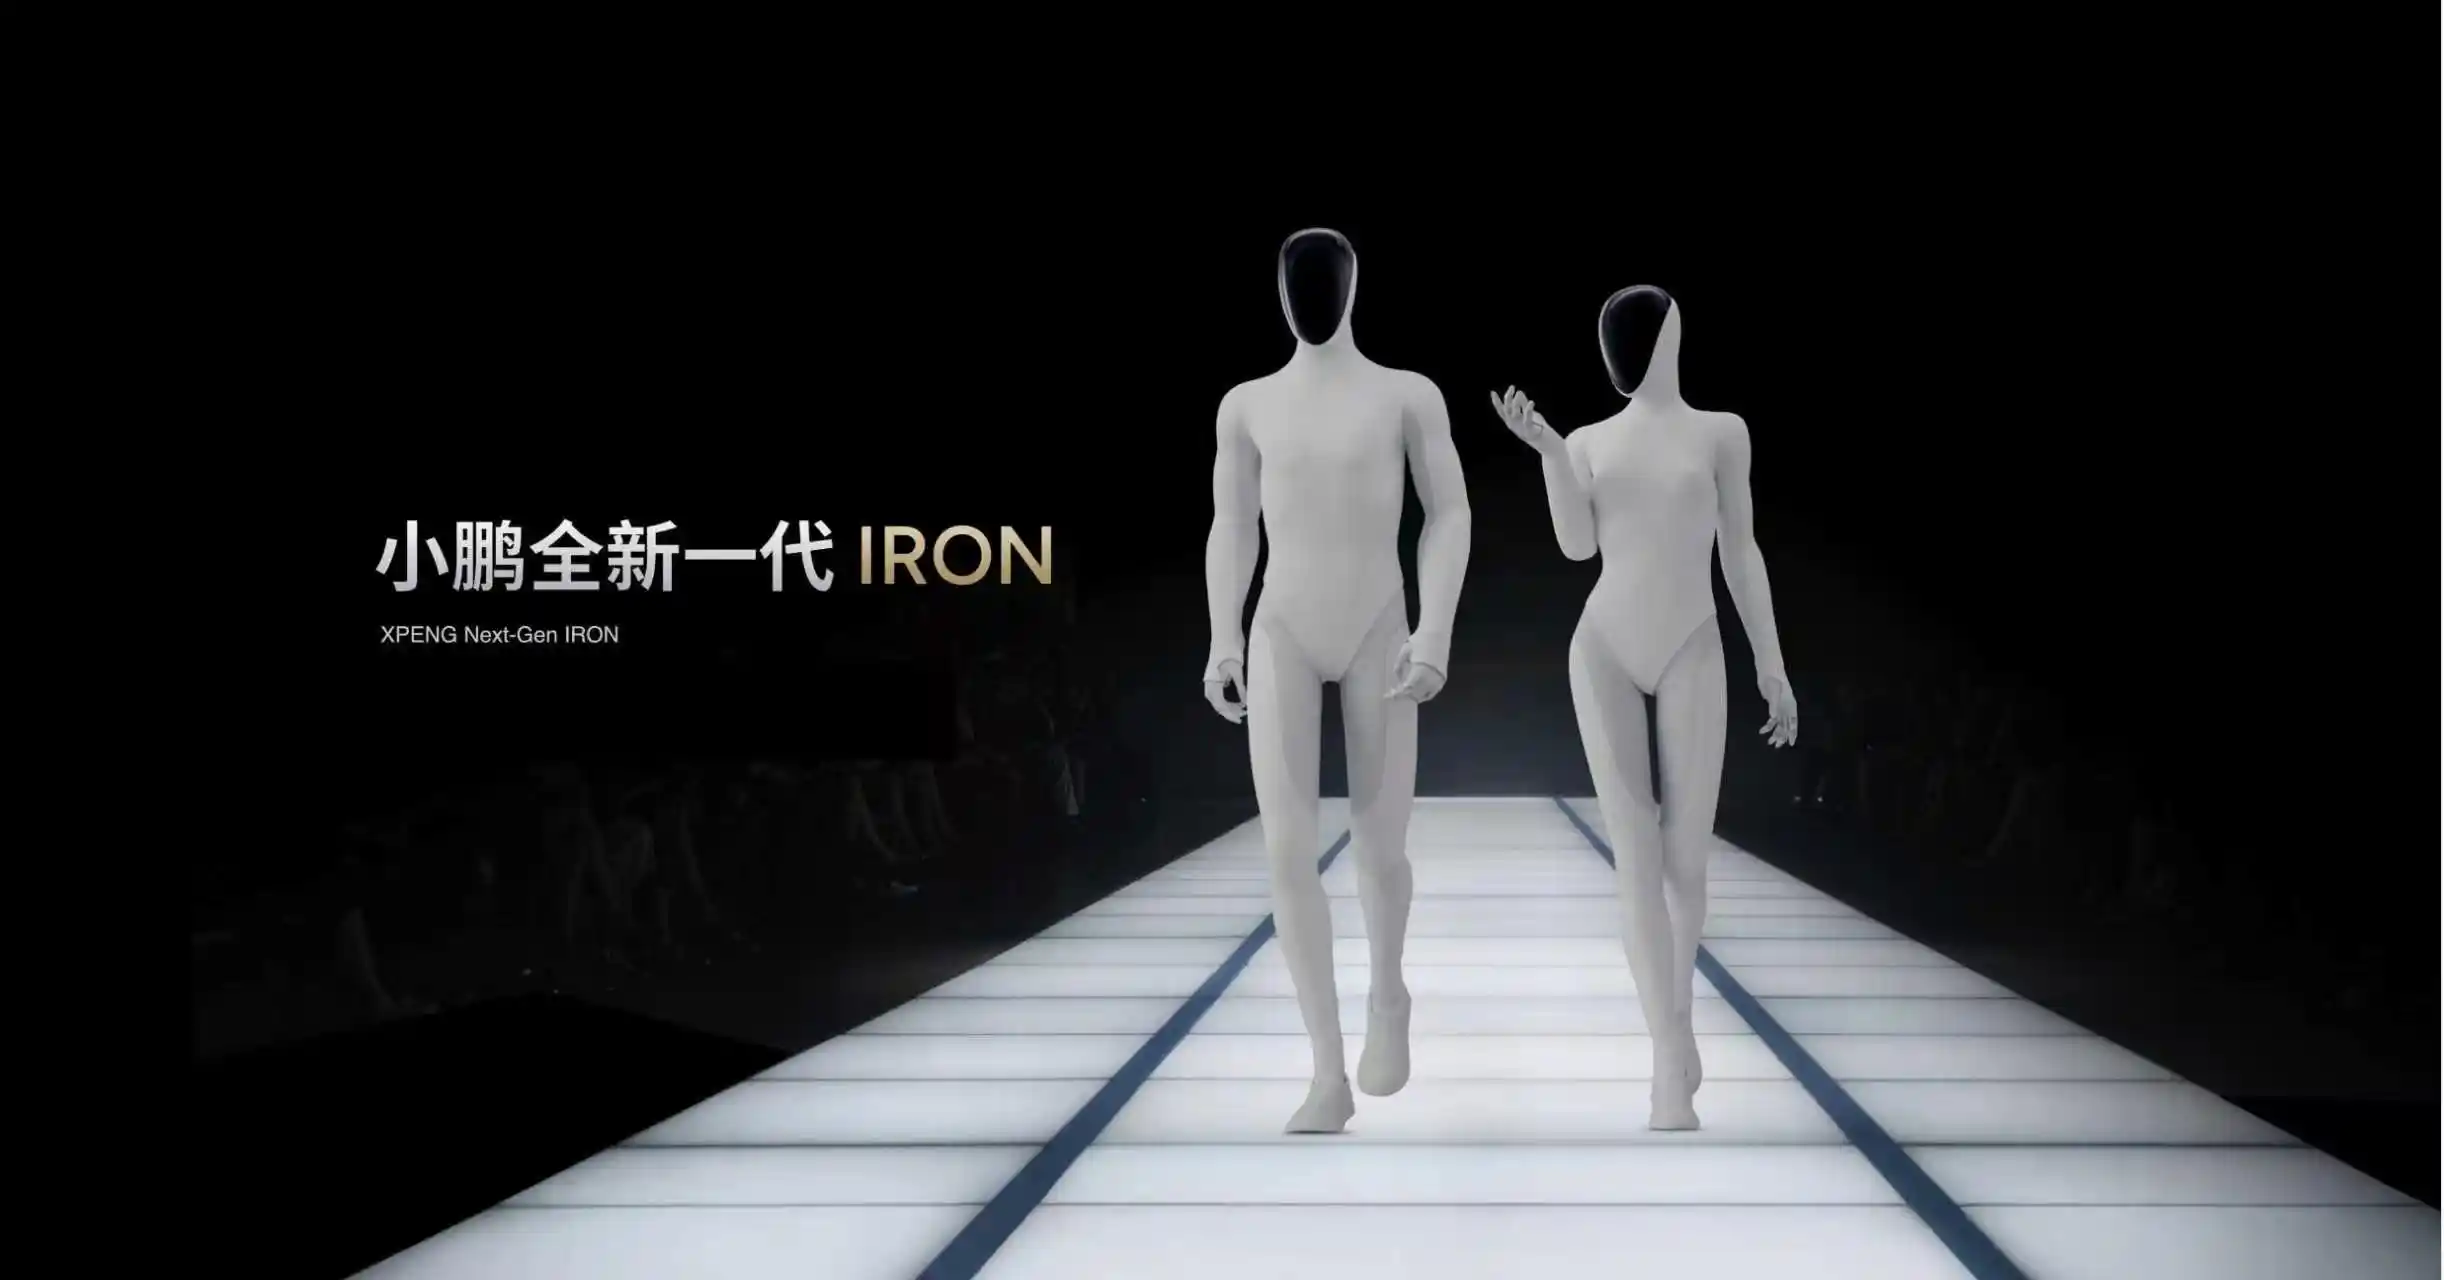
Companies operating in both automotive and robotics sectors can amortize chip R&D costs across two product lines. Take XPeng as an example—its IRON robot and XPeng vehicles share identical Turing chip configurations. The cumulative shipping volume of Turing chips has surpassed 200,000 units, almost entirely from automotive applications, with R&D costs primarily borne by the automotive business. Reports indicate the per-unit manufacturing cost of the Turing chip has dropped to between RMB 2,500 and 3,000.
For embodied intelligence firms whose primary revenue stream comes from robot sales, designing chips that precisely meet system requirements presents a complex engineering challenge—one that can be addressed through sustained investment.
More critical is the question: Can in-house development deliver better cost efficiency than procuring off-the-shelf chips? Only through consistent order volume and scaling deliveries can firms spread R&D costs across enough units to achieve cost advantages. This places higher demands on their commercialization capabilities.
Source: Fourth Wave Technology
Disclaimer: Contains third-party opinions, does not constitute financial advice


HuggingFace's "AI Duck" Goes Viral, Boosting Chinese Chip Supplier Rockchip
09-02
Yushu Surges 629% on First Day of Trading, Humanoid Robots Sell 5,500 Units
08-19
14 Executives Depart, Horizon Unleashes a Robot Legion
08-11
Nokia Snatches AI Optical Chip Race, Stock Soars 52%
08-07
Yushu's 61 Billion IPO: Who Will Make Money?
08-07
AI stocks down 40%-60%, yet NVIDIA's valuation is at a 10-year low
08-06
HBM Bottleneck Migration, NVIDIA Also Aims to Downgrade
08-06


