AI Short Films Surpass 500,000 Annual Releases—Who Captures the Majority of the Profits?
AI Short Films Surpass 500,000 Annual Releases—Who Captures the Majority of the Profits?

2026-11-15 16:06
Introduction: Content producers bear compute costs and ad spend, platforms control revenue sharing and IP licensing fees. For the film and television industry in 2026, no single event can encapsulate the year.
For the film and television industry, 2026 defies summary under a single narrative. It lacks the sudden boom-and-bust tech story of past years. Video generation capabilities began entering production pipelines early in the year, and by year-end, their impact had extended beyond production into financing, distribution channels, organizational models, and profit allocation.
At the start of the year, Seedance 2.0 was launched. Its most notable feature was controllability. Creators could now specify characters, scenes, and shot styles—transforming what once required iterative trial and error into a process with predictable cost, timeline, and deliverable outcomes.
This shift quickly reached capital markets. In July, Kuaishou spun off its KeLing AI assets for a separate funding round, achieving a post-money valuation of approximately $18 billion. Shengshu Tech and Aisai Tech also completed fundraising rounds within the year. Video models thus transitioned from internal corporate functions to independently valued assets.
Once video generation technology acquired market pricing, content supply expanded significantly. Short-form series, due to short production cycles, mature monetization models, and relatively lower demands on visual continuity, emerged as the first category to scale rapidly. Over 500,000 AI-generated short series were launched this year; the breakout success of *Armed into Song* further demonstrated the potential for small teams to create viral hits.
Yet increased supply did not translate into broader profitability for creators. Platforms retain control over traffic and revenue-sharing mechanisms, while upstream IP holders earn licensing income. Midstream producers shoulder the burden of compute power and ad spend. As production barriers fall, profits increasingly concentrate in the hands of a few companies that dominate distribution and intellectual property rights.
Traditional film and television players were also pulled into this transformation. Directors such as Jia Zhangke and Lu Chuan publicly showcased AI-driven works. Mango TV and Bona Film Group brought AI-produced long-form series and films to broadcast and theatrical releases respectively. iQiyi integrated scriptwriting, art direction, and editing into an intelligent agent platform.
The results from these experiments remain uneven. Production efficiency has indeed improved, and costs have dropped—but audience expectations regarding character emotion, narrative pacing, and aesthetic completeness have not diminished. Long-form series and feature films expose this tension more directly. Tools can accelerate visual output, but storytelling still requires human judgment.
Overseas markets offer another benchmark. OpenAI shut down Sora, Netflix acquired InterPositive, and Hollywood guilds continue renegotiating terms around AI usage and compensation. Unlike China’s focus on scale and speed-to-market, the U.S. entertainment industry is more concerned with how human contributions are recognized and compensated when AI enters production workflows.
When viewed collectively, the events of 2026 reveal that the film and television industry is undergoing far more than a simple tool replacement. Rules governing production cost, capital valuation, and profit distribution are shifting. The traditional order—once maintained by production crews, studios, platforms, and theaters—is beginning to unravel, replaced by a new system built around models, compute power, and traffic.
This is the real landscape left by intelligent migration in the film and television sector as we enter 2026.
01. From Random Generation to Control: Capital Begins Assigning Clear Prices
The launch of Seedance 2.0 stands as one of the most pivotal milestones in the video model industry this year.
On February 12, ByteDance’s Seed team unveiled Seedance 2.0. The new model adopts a unified multimodal audiovisual joint generation architecture, supporting four input modalities: text, images, audio, and video, and integrates reference-based generation and editing into a single pipeline.
The industry’s primary focus, however, lies in its controllability. Creators can now specify character appearance, scene atmosphere, and camera movement using reference materials, drastically reducing the number of iterations needed to generate usable footage—and enabling more accurate cost and timeline estimation.
Before this, AI video generation resembled unpredictable experimentation. Identical prompts could yield vastly different outputs, leaving creators unable to consistently control quality, and buyers incapable of setting budgets or delivery timelines.
Seedance 2.0 transformed generation into a manageable process. For the film and television industry, this marks the moment AI video became viable for formal production workflows—costs can be forecasted upfront, schedules planned, and deliverables verified.
Capital’s willingness to revalue the asset stems precisely from this predictability. Only when output becomes foreseeable can video models be treated as stable production inputs. Once they begin influencing production cost structures, their commercial value gains clearer metrics.
Model iteration continues at breakneck speed; Seedance 2.0 and 2.5 remain in the top tier. Video generation represents one of the few areas where Chinese firms maintain sustained leadership over Silicon Valley counterparts, drawing heightened commercial interest. In November, sources close to Volcano Engine confirmed that Seedance’s overseas revenue share had reached 50%, with overseas income growing nearly fivefold in the past six months. Domestically, internet enterprises are the primary buyers, with Tencent ranking among the top three clients in China.
Yet this client structure itself warrants attention. Even other internet giants possessing comparable model capabilities are purchasing Seedance, indicating a clear efficiency advantage held by leading models. For many competitors, continuing independent R&D may prove less economical than outright procurement.
In the first half of the year, Seedance 2.0 enabled AI video to enter budget-conscious production. In the second half, Kuaishou’s spin-off of KeLing AI assets marked the first time capital assigned standalone valuations to such assets, culminating in the largest single-round financing record ever for a global video generative model company.
In July, Kuaishou introduced external investment of up to $3 billion into KeLing AI assets at a pre-money valuation of $15 billion, resulting in a post-money valuation of ~$18 billion. By November, the capital raise was officially confirmed as completed.
A key driver behind this transaction may have been the valuation gap between KeLing AI and its parent company. Post-money valuation of KeLing AI already exceeded Kuaishou’s market cap. The original business’s valuation framework proved inadequate for accommodating faster-growing AI assets, making divestiture the most direct path to unlock value.
These developments collectively illustrate how the growth rate of technological assets is now reshaping corporate structures. When AI divisions outpace the valuation logic of their parent companies, firms must adjust equity and asset configurations. This accelerates the commercialization timeline for video models.
Progress by secondary players in the capital market confirms that competition is no longer confined to tech giants.
Minimax listed on HKEX in January and initiated A-share IPO counseling in May, aiming for dual listing on both A+H platforms. HaiLuo AI holds technical credibility in video generation, but Minimax’s capital narrative has shifted toward B2B token revenue and full-modal platform development.
In primary markets, Shengshu Tech completed multiple rounds of financing and advanced its shareholding reform within the year, focusing on real-time generation and world models. Aisai Tech raised nearly ¥3 billion cumulatively in Series C, with over 150 million global users and annual recurring revenue exceeding $40 million. Yanyu Tech secured nearly $300 million in Series B+ funding in June, achieving a post-money valuation above $2 billion. Sand.ai, pursuing a self-regressive technical path, recently closed a $50 million round, with annual recurring revenue surpassing $10 million.
These companies no longer compete head-on with giants on general-purpose generation. Instead, they target niche entry points like real-time interaction and world modeling, proving independent valuation through concrete revenue. Their fundraising progress and IPO rumors provide stronger benchmarks for primary markets, pushing video model firms earlier into revenue- and profit-focused evaluation stages.
However, after securing funding and going public, video model vendors will face stricter scrutiny. The prices set by capital must ultimately align with future revenue and cash flow. Currently, AI video revenue remains concentrated in limited scenarios such as short-form series and ad creatives, with high customer concentration.
What capital offered this year was largely access credentials. The real test for next year lies in whether these companies can establish stable customers and consistent revenue during the window of opportunity, preserving their early technological edge. If model gaps narrow while commercialization lags, high valuations will become unsustainable.
02. AI Short-Form Series Supply Surge, But Profit Distribution Reaches Limits
As model capabilities meet industrial delivery requirements, competition in AI video shifts from creative novelty to delivery performance. The ability to deliver content on time, to specification, and at required quality now outweighs mere visual fidelity. With procurement methods becoming clearer, AI video is evolving into a quantifiable foundational service.
In 2026, short-form series were widely seen as the ideal format for AI video deployment. They feature short production cycles, transparent cost structures, well-established monetization paths, and lower demands on emotional continuity and artistic precision compared to long-form series and films. These traits made them the preferred choice for rapid revenue validation across all stakeholders.
AI short-form series leveraged existing infrastructure from live-action series—ad monetization, user subscriptions, platform revenue sharing, and IP derivatives. Hongguo Short Drama rapidly scaled via TikTok’s traffic entry point; by July, its daily active users surpassed those of major long-form video platforms.
Later in the year, a small-team project revealed another possibility.
*Armed into Song* relied neither on massive ad spend nor early hype. The first season launched on Hongguo in August 2023, initially underperforming. Starting from the fourth season, it regained momentum through word-of-mouth and climbed to the top of Hongguo’s AI New Series chart. After the tenth season release, the series became a true blockbuster, amassing over 4 billion views by November 6.
The IP originated from the free copyright library of Tomato Novel, previously unremarkable. The core team consisted of only six members: a stay-at-home mom, ride-hailing driver, delivery contractor, wholesale trader, and regular office worker. Distributed across different cities, none had formal film training. They collaborated entirely online, splitting rewards based on effective runtime.
The team’s main investment went into compute resources, with total series cost exceeding ¥1 million. Such a spending pattern is uncommon in an industry reliant on ad-driven acquisition. Yet *Armed into Song*’s success proves audiences do not inherently reject AI technology. What they reject is poor production quality and low-grade content. As long as the story holds, the “AI-made” label does not automatically deter viewers.
*Armed into Song* is just one of over 500,000 AI short-form series released this year—rare successes amid rapid supply expansion. While model capability release fuels prosperity, the industry’s impact centers on changes in distribution and profit allocation.
Supply growth approached explosion levels, yet profits failed to reach most creators. AI compressed overall production costs to roughly one-tenth of traditional live-action filming, reducing per-minute production cost for web series from over ¥2,000 to ¥150–800. However, cost savings weren’t evenly distributed. In the first half of 2026, among newly launched AI short series on Douyin, only 0.48% achieved over 100 million views, and just 1.3% reached breakeven—roughly one in every 77 titles. Industry-wide average gross margin was estimated as negative.
These figures show value concentrating at the IP and platform ends. Upstream IP holders receive licensing and adaptation fees, downstream platforms control traffic allocation and revenue-sharing rules, while midstream producers absorb compute and ad spend—becoming the most heavily invested and least stable-return segment.
The late-year debate over “ByteDance Time” pushed this dynamic into sharper focus. Financial commentator Qin Shuo cited Nomura Securities data on user time, arguing China’s internet era is transitioning from Tencent Time to ByteDance Time. Douyin Group VP Li Liang rejected the data methodology and implied monopoly claims, escalating his rebuttals from “extremely sloppy” to “either stupid or malicious,” eventually leading to legal proceedings.
Beyond the dispute itself, the deeper issue lies in the industry’s structural position. When platforms simultaneously control traffic gateways, revenue-sharing rules, and compute supply, user attention and creator income inevitably converge toward them. Since the live-action series era, the short-form industry has grappled with the same dilemma: platforms set the rules and capture the lion’s share of benefits. Who should ensure sustainability of the content ecosystem?
If this question remains unresolved, the prosperity driven by AI short-form series will remain confined to volume alone, offering little benefit to the broader content ecosystem. If gains from technology cannot be fairly distributed across the value chain, the very content supply that platforms depend on will ultimately suffer.
This year, the industry has validated AI short-form series’ feasibility on the production side. The harder challenge ahead lies in establishing fairer reward mechanisms on distribution, ensuring that technological efficiency translates into sustainable content supply.
03. Traditional Film & TV’s Long-Cycle, High-Investment Model Begins to Crumble
AI’s impact extends beyond production workflows—it is destabilizing the cost structures and organizational models long embedded in the film and television industry. In 2026, veteran filmmakers began cautiously exploring transformation, varying in scale but no longer able to remain spectators.
AI tools simultaneously compress production timelines and lower financial thresholds. The old operating model—based on long cycles, high investment, and heavy assets—is weakening. Some projects now mirror internet product rhythms: small-scale validation first, followed by content adjustments based on market feedback. The traditional industry habit of big bets with high confidence is losing its foundation.
Jia Zhangke, one of China’s foremost film directors, was among the earliest to act. During the Spring Festival, he released *Director Jia Dance*, an AI-generated short film created in collaboration with Seedance 2.0. Two versions of Jia Zhangke appear in the film—one clearly stylized by AI, the other near-indistinguishable from reality.
The short film forces a central question onto the industry: if visuals can be continuously generated by AI, what remains of the director’s role? Jia’s involvement brought video models into the core discourse of the film industry. Those who once discussed release dates, actors, and box office now must confront a technology reshaping production methods.
Larger shifts come from platform and studio-scale initiatives. In September, Mango TV’s *After Journey to the West*, produced entirely via AIGC, became China’s first AI-generated series to air on national television. In October, Bona Film Group’s *Future Past of Sanxingduo* received the official “dragon mark” and entered nationwide theaters, bringing AI cinema from streaming platforms to ticketed venues.
AI dramatically reduces production costs, eroding the high barriers once maintained by large capital and heavy assets. But content shortcomings are exposed more clearly.
After *After Journey to the West* aired, audiences praised its guofeng visuals but criticized obvious AI artifacts and flat plotlines. The director admitted the hardest challenge was maintaining emotional continuity. *Future Past of Sanxingduo* received colder reception, with distributor revenue falling below 10% of production cost.
The roughness tolerable on short-form screens becomes amplified on the big screen. Storytelling ability cannot be achieved in a single generation—a domain where film and television remains hardest to automate.
These attempts also raise another critical issue: can AI help creators evolve narrative techniques and aesthetic experience? The answer remains uncertain.
Previously, a top-tier series might take years from concept to broadcast. Long timelines ensured quality and allowed room for course correction. Creative inspiration rarely follows schedule, but ample budget and time permitted continuous revision.
Fast production follows a different set of rules. It encourages small-scale testing for feedback, then uses data to determine next-round investment. Yet narrative depth, aesthetic taste, and emotional resonance rely on long-term accumulation—they cannot easily be broken into iteratively refined modules.
Thus, the industry finds itself in a somewhat awkward phase: production speed increases rapidly, but content substance struggles to keep pace. The real threat isn’t necessarily those refusing to use AI, but those who only use it to cut costs without offering fresh stories or telling old ones compellingly.
More top-tier directors continue experimenting. Lu Chuan premiered the teaser for his AIGC short film *History·Live* at the 2026 Yunqi Conference, reconstructing the 1626 disaster at Wang Gong Factory in Ming Dynasty. He believes AI enables visualizations impossible under prior budget constraints. For creators, the real value lies in expanding visual imagination—not just reducing labor and location expenses.
Directors, producers, theaters, and platforms are all probing AI’s boundaries. But what truly determines how far this chain can go remains platform-level decisions.
This year, iQiyi founder and CEO Gong Yu announced the company’s transformation into a decentralized social media platform, launching a professional production platform covering scriptwriting, directing, art direction, and editing, along with nearly 70 intelligent agents. The platform also opened its IP library, digital asset repository, and an AI talent pool with over 100 artists already onboard. The goal: turn individual project experiences into reusable production infrastructure.
With directors, studios, theaters, and platforms all engaged, these 2026 experiments resemble a collective stress test. The industry witnessed how far efficiency can rise—and where narrative capacity reveals its limits.
Efficiency advantages are easily replicated by peers, and tool-driven gains gradually dilute upon widespread adoption. In contrast, non-standardizable elements like creativity, aesthetic judgment, and critical thinking form deeper, longer-lasting moats. Ultimately, film and television competition returns to a fundamental question: what kind of story do we want to tell?
04. Hollywood Is Redefining AI Boundaries—Paths Diverge from China
While Chinese firms accelerate model advancement and industrial deployment, the overseas film and television sector exhibits a different rhythm. Some companies exit consumer video products, platforms reprice AI capabilities, and unions continue defining the boundaries of human labor.
In March, OpenAI announced the shutdown of Sora, ending its collaboration with Disney. Publicly, the reason cited was resource allocation; more directly, the operational cost of video models proved too high, and consumer-level revenue couldn’t justify ongoing investment.
Sora’s exit doesn’t signal failure of the video model approach. Rather, it reflects OpenAI’s recalibration of commercial priorities—redirecting GPU resources toward higher-revenue-generating businesses.
Earlier in the large model industry, competition centered on “can we do it?” Now, more companies must first ask “is it worth doing?” Technical feasibility alone can no longer sustain long-term investment. Only pathways generating stable revenue can persist.
Following Sora’s closure, several core team members joined DreamWorks co-founder and others to launch a new company, aiming to develop professional tools tailored for film production. The focus of video models thus shifts from mass-consumer products to cinematic production pipelines.
This shift signals that professional creators are willing to pay for enhanced efficiency. For many AI application firms, generic capabilities struggle to generate direct revenue. Only by entering specific industries and solving concrete cost problems does commercial value become tangible.
Overseas capital is also reassessing AI video. This year, Netflix acquired AI video company InterPositive in a deal far exceeding its historical norms. The company specializes in optimizing library production efficiency using licensed content libraries. The transaction sends a clear message: Hollywood streamers view AI primarily as production infrastructure to enhance content management efficiency.
This contrasts sharply with KeLing AI’s $18 billion post-money valuation. Chinese capital favors spinning off fast-growing AI assets, whereas Hollywood companies prefer integrating AI as a supplementary function within existing production systems.
Hollywood’s adjustment goes beyond tool usage—it also redefines human roles. Three years ago, writers’ and actors’ guilds won AI protection clauses through prolonged strikes. Today, these clauses are being reinterpreted case by case. Guild demands have evolved from restricting use to requiring compensation for use. Writers’ guilds seek payment for scripts used to train models; actors’ guilds demand proof that synthetic performers add significant value.
This evolution indicates Hollywood has accepted AI’s presence in production. The next challenge is determining how to measure human contribution post-AI integration and how to allocate compensation accordingly.
This is an unavoidable issue in intelligent migration. As compute handles more execution tasks, human creativity, aesthetic judgment, and emotional expression require new valuation frameworks. Who defines the value of these abilities, and how is it codified into contracts and compensation standards? This directly shapes future profit distribution in content industries. Guild negotiations are transforming abstract human contributions into enforceable terms.
New companies are emerging amid these rule changes. Utopai Studios, a Silicon Valley AI film studio, completed a major funding round and is now considered one of the world’s largest independent AI-native film companies. More importantly, it became the first AI film company to join both the Writers Guild of America and Screen Actors Guild, earning eligibility to enter the Hollywood production system. Utopai refuses to define itself as a model company; its generative models are customized based on China’s MiniMax H3, ranking among the top in blind video evaluation benchmarks.
This company’s path is representative: model capabilities can be delivered globally, but capital, talent, and industry rules must be earned locally. Technological foundations originate in China, while commercial legitimacy is validated through Hollywood guild systems. Globalization and localization of intelligent migration proceed simultaneously. Companies capable of bridging both will command strategic advantage in the next phase.
Hollywood and China’s AI video industries represent two distinct trajectories. China leads in model capability and rapid industrial deployment. The U.S. has scaled back some consumer-facing model operations, redirecting capital and talent toward AI-native studios. Chinese firms prioritize leveraging lower costs to gain channel access; American firms rely on established teams to secure rule recognition.
More strikingly, the two paths are now confronting issues the other has yet to resolve. China must answer questions about profitability and distribution models after scaling growth; the U.S. must determine how rule protections leave room for innovation. The changes already underway in 2026 demonstrate that competition is no longer solely about technical prowess—it also hinges on institutional design and industrial organization. Future companies that endure will need compelling stories—and the ability to transform every unit of compute into emotional resonance genuinely felt by audiences. (This article originally published on Titanium Media APP, by LccBeta)
----------------------------------------------------------------------------------
Who will be the first to deliver results in the AI-driven industry overhaul? Titanium Media’s “Intelligent Migration” series explores ten pivotal questions, tracing how AI transitions from model competition to real-world applications across industries. We’ll soon compile more topics, comparing tech trends and industry insights between China and the U.S., to examine intelligent migration across sectors.
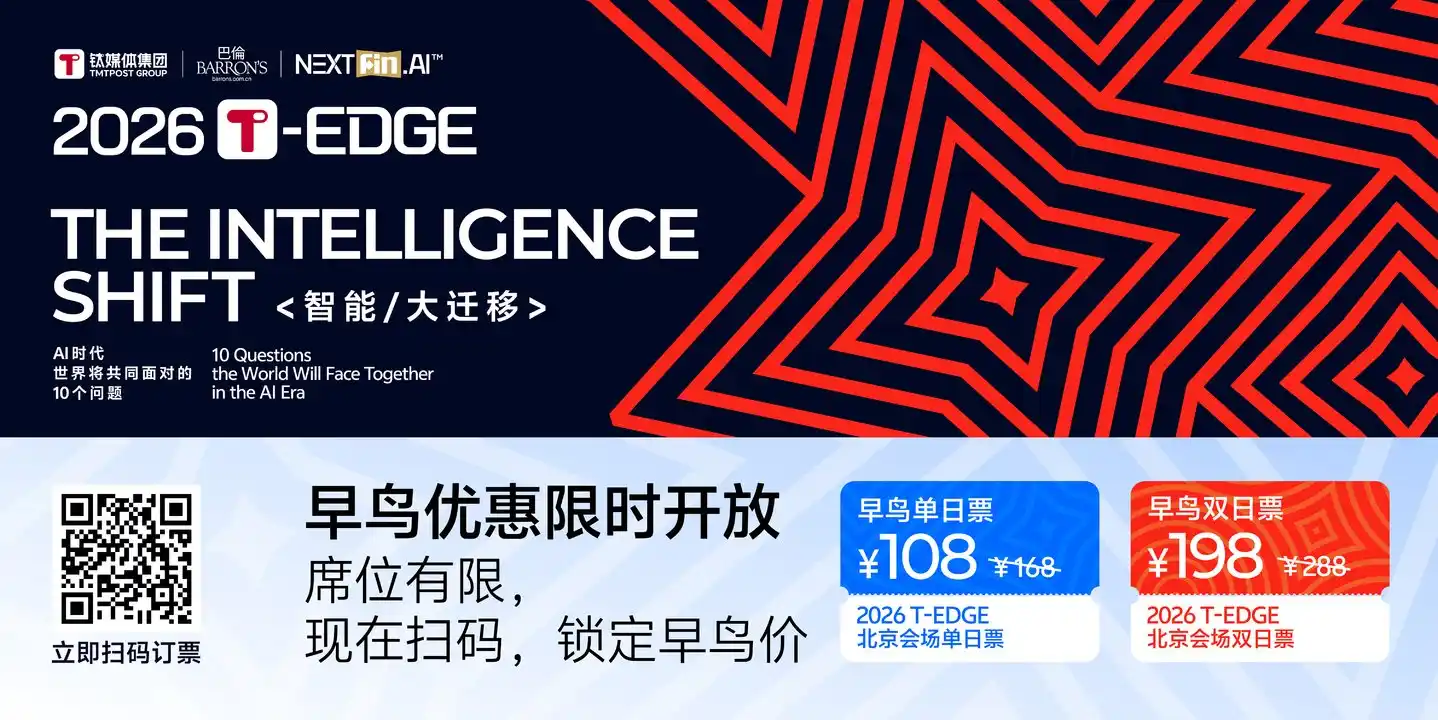
2026 T-EDGE Innovation Summit | Cultural & Film & TV Segment
From generating a single shot to completing a full production—what hurdles remain? This question will be explored live at T-EDGE. Renowned directors, screenwriters, producers, and chief AI scientists will share firsthand insights on what AI truly brings to a production.
Time: December 8, 2026 (Beijing Time)
Location: Zhongguancun Exhibition Center, Beijing
Want to discuss face-to-face with them? Join us at the 2026 T-EDGE Innovation Summit. Scan the QR code below to explore event details and purchase tickets!
Source: LCC_Beta Edition
Disclaimer: Contains third-party opinions, does not constitute financial advice


Yushu Surges 629% on First Day of Trading, Humanoid Robots Sell 5,500 Units
08-19
Yushu's 61 Billion IPO: Who Will Make Money?
08-07
AI stocks down 40%-60%, yet NVIDIA's valuation is at a 10-year low
08-06
HBM Bottleneck Migration, NVIDIA Also Aims to Downgrade
08-06
AI Servers Fuel Demand for Minor Metals: Prices Surge Over 70% in Half a Year
08-06
Cloud vendors first declined then surged—why the divergence in AI assets?
08-05With AI optical modules, Shandong's new richest man secures the largest IPO on Hong Kong stock market this year
07-30


