Goldman Sachs Bullish on China's AI: 4 Trillion Only Accounts for 1.2%
Goldman Sachs Bullish on China's AI: 4 Trillion Only Accounts for 1.2%

TL;DR
Goldman Sachs recommends buying a basket of Chinese AI value chain assets, covering power, semiconductors, AI infrastructure, models, and applications.
Goldman estimates that China’s AI-related market capitalization is approximately $4 trillion, contributing about 16% to global AI-related revenue, while global mutual fund tech exposure to China remains only around 1.2%.
The core of this trade is not a single AI application breakout, but rather the re-rating opportunity driven by underweight positioning, policy investment, and hardware demand.
Risks lie in the continued need for execution on data center investments, storage expansion, IPO financing, and AI hardware exports.
Goldman’s thematic research team is pushing the “China AI Value Chain” into the forefront of trading visibility.
In its report titled “Trading Strategy: Long the China Artificial Intelligence Value Chain,” Goldman recommends long exposure to a China AI basket encompassing power, semiconductors, AI infrastructure, models, and applications. Over the past two years, global AI trading has been dominated by U.S. mega-cap tech stocks, NVIDIA supply chains, and cloud capex. Now, Goldman identifies a mispricing between market cap, revenue contribution, and global fund holdings in Chinese AI assets.
According to Goldman’s estimates, Chinese AI-related companies already have a market cap of about $4 trillion, accounting for roughly 16% of global AI-related revenue, yet as of January 2026, global mutual fund managers’ allocation to China within their global tech exposure stood at only about 1.2%.
This set of figures forms the central trading logic of the entire report: if China’s AI industry already holds double-digit revenue share globally, while global fund allocations remain significantly underweight, there exists substantial room for re-pricing of the China AI value chain.
Biggest Discrepancy: High Revenue Contribution, Low Global Fund Allocation
Goldman’s breakdown of global AI assets presents a stark comparison.
Since late 2022, global AI-related equities have generated approximately $34 trillion in market cap, with China’s AI-related segment accounting for about $4 trillion, or roughly 10% of total global AI-related market cap. In terms of revenue, China contributes about 16% of global AI-related revenue.
Fund allocation, however, lags far behind this proportion. Goldman estimates that as of January 2026, global mutual fund managers’ allocation to China within their global tech exposure was only about 1.2%.
This is the core rationale behind Goldman’s recommendation to go long on the China AI value chain. U.S. AI assets have already been repeatedly bought by global capital—NVIDIA, cloud providers, semiconductor equipment, and power infrastructure are all embedded in the AI trade narrative. In contrast, despite having established a meaningful revenue scale, Chinese AI assets remain underweighted in global fund portfolios.
In other words, Goldman is betting not just on a “China AI story,” but on a more precise asset allocation gap: revenue contribution has materialized, but global holdings have yet to catch up.
This Is Not Traditional KWEB Trade — Hardware and Infrastructure Take Priority
Goldman emphasizes that this trade differs fundamentally from traditional KWEB-style investing.
KWEB typically reflects exposure to China’s internet and platform economy—investors think of e-commerce, advertising, online entertainment, and local services. However, Goldman’s current construct is the GS China AI Value Chain (GSXACART) basket, spanning power, semiconductors, AI infrastructure, models, and applications—closer to a complete Chinese AI supply chain.
Under this framework, hardware and infrastructure take precedence.
China’s push for technological self-reliance and advanced computing capabilities has brought simultaneous policy, industrial, and capital attention to AI hardware, data centers, power infrastructure, and semiconductor segments. Goldman believes these segments’ value remains insufficiently reflected in stock markets.
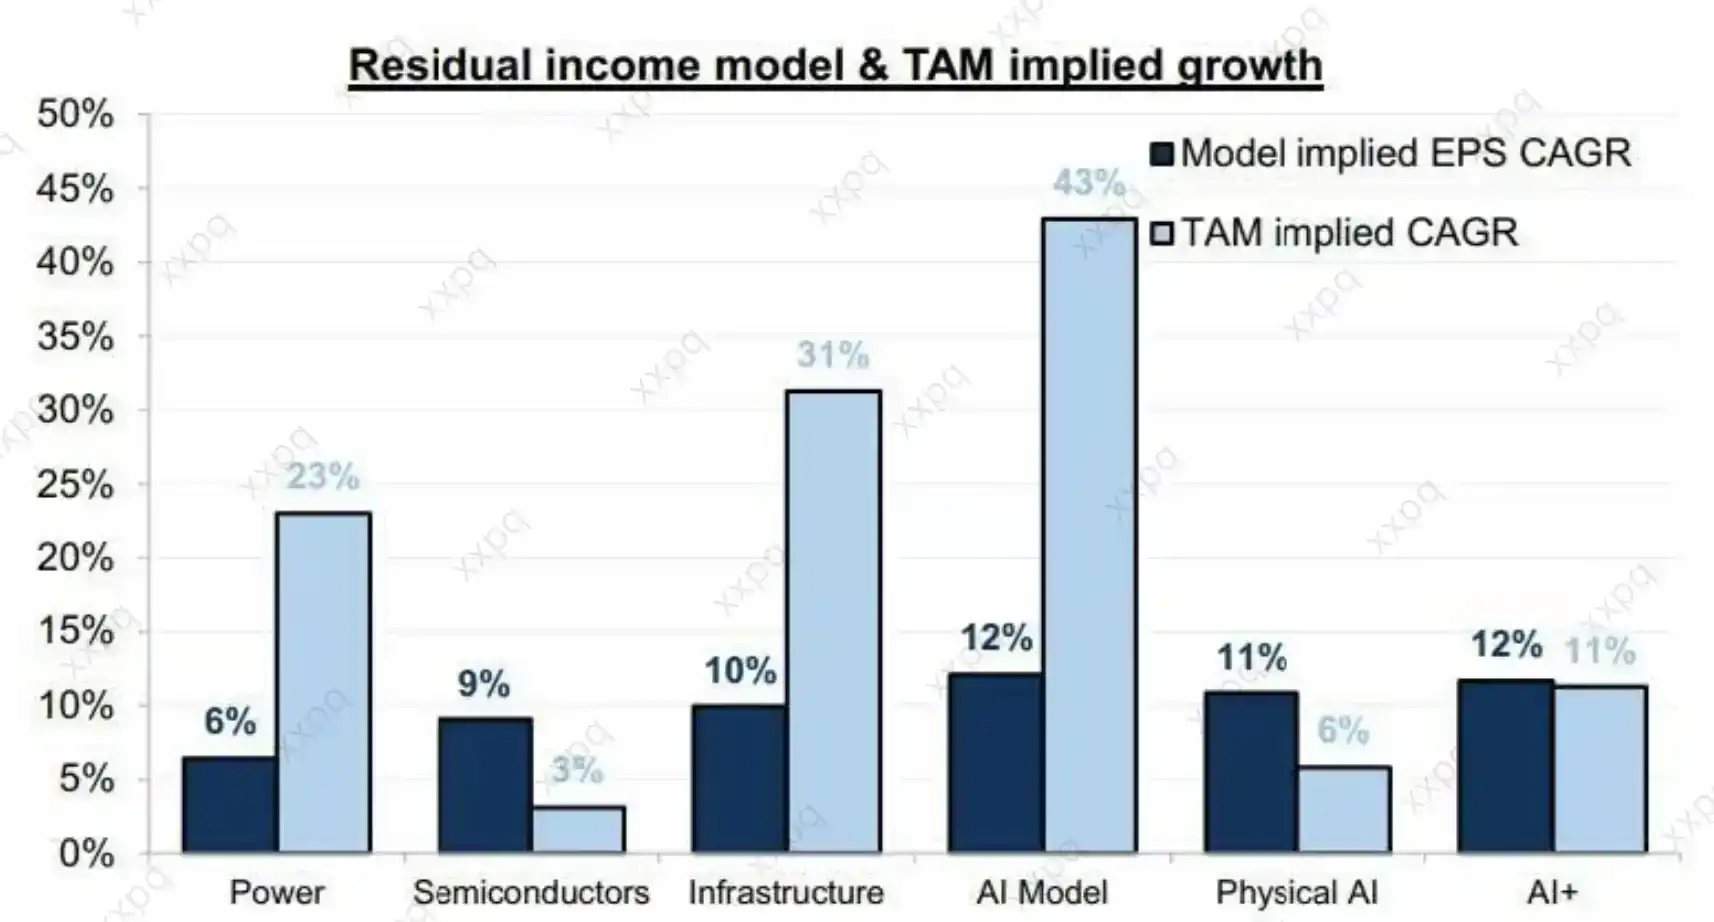
Its research estimates that the potential economic upside from AI-driven efficiency gains and new profit creation could be 50% to 100% higher than what is currently priced into AI equities. This explains why power, AI infrastructure, and semiconductors are placed at the core of the basket.
Whether models and applications can break out ultimately depends on compute, storage, power, and equipment supply. These are precisely where China excels in large-scale manufacturing, engineering, and industrial ecosystem support.
Exports, Policy, and IPOs Are Reinforcing the AI Hardware Thesis
Changes in China’s AI hardware chain are shifting from concept to tangible order, export, and financing milestones.
On the demand side, media reports citing customs data show China’s exports rose 19.4% year-on-year in May—the strongest increase in three months. Among them, integrated circuit exports surged nearly 111% year-on-year, while volume growth was modest. Behind the price and structural shifts, AI hardware demand is seen as a key driver. For memory, semiconductor equipment, and upstream materials, such data suggest improving orders and capacity utilization.
On the policy investment front, Reuters cited Bloomberg reporting that China is preparing a five-year plan worth approximately RMB 2 trillion (~$295 billion) to build a nationwide AI data center network. Although not formally announced, if implemented, it would directly drive domestic demand for storage chips, semiconductor equipment, power infrastructure, and data center construction.
In capital markets, public reports indicate that A-share, Hong Kong-listed stocks, and certain global indices have increased weights on AI and semiconductors in 2026 rebalancing. This will enhance passive fund visibility for related firms and attract more domestic and international capital toward advanced computing and semiconductor sectors.
Individual company and industry cases are further reinforcing this thesis. Yangtze Memory Technologies reported Q1 2026 revenue up ~445% YoY, with its global NAND flash market share rising from 8% a year ago to 13%, placing it jointly fourth globally, and advancing plans for an onshore IPO to support capacity expansion.
ChangXin Memory is viewed as a pivotal player in China’s DRAM industry. Third-party research estimates its 2026 revenue may exceed $50 billion; company filings show Q1 revenue at RMB 50.8 billion, with H1 2026 guidance ranging from RMB 110 to 120 billion.
These cases do not imply that Chinese memory firms have fully caught up with overseas giants, but they demonstrate that China’s AI hardware chain is evolving from a “policy concept” into observable nodes of revenue, market share, financing, and capacity expansion.
Funds Are Shifting — U.S. AI Remains Primary Benchmark
Goldman also notes that the Chinese AI sector has already outperformed other China-related assets and shows signs of capital reallocation. Nevertheless, compared to U.S. AI, Chinese AI assets still lag significantly.
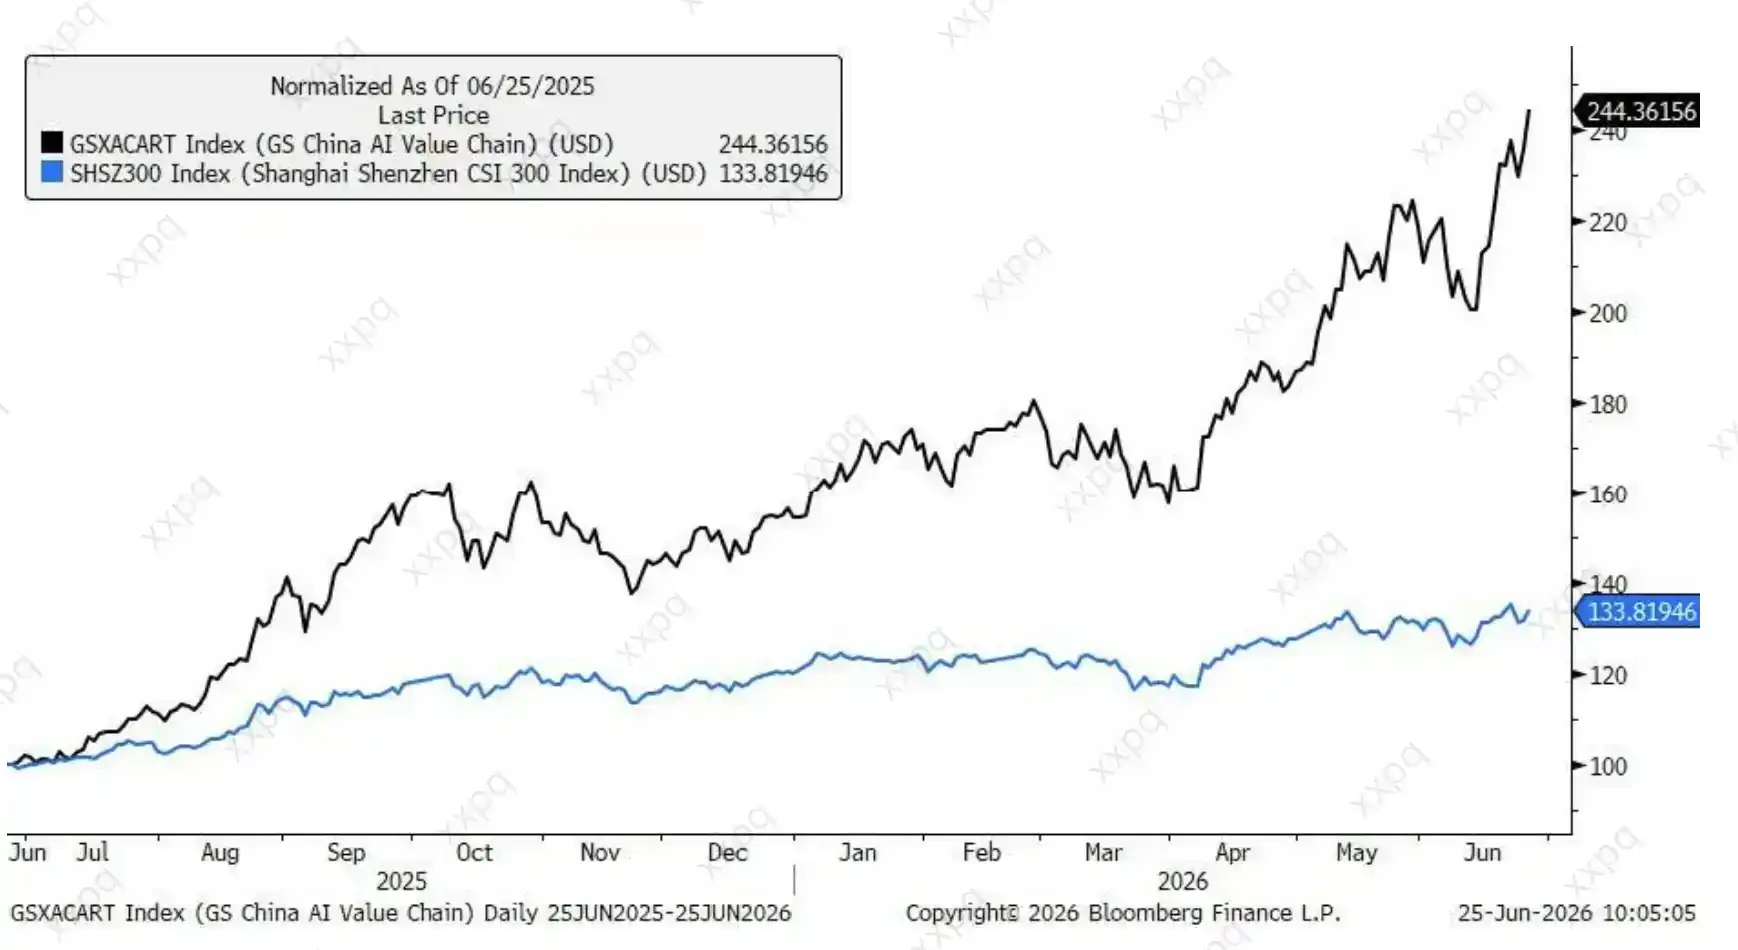
This is where both the appeal and risk boundaries coexist.
The appeal lies in the fact that if global investors continue seeking growth beyond U.S. AI, China’s underweight status may leave room for capital rotation. Especially after U.S. AI leaders have high valuations and capex expectations have been widely priced in, the market naturally seeks undervalued supply chains and application assets that remain under-owned.
The risk is that this remains a trade idea, not a confirmed industrial conclusion. The RMB 2 trillion AI data center plan hinges on policy details and actual execution; IPOs, capacity expansions, and profitability improvements at companies like ChangXin and Yangtze Memory require time; and sustained chip export and sales performance depend on the global AI hardware cycle and trade environment.
U.S. AI remains the primary benchmark for global capital. Whether in model capability, cloud capex, GPU ecosystems, or enterprise application revenue, the U.S. market still sets the gold standard. For China AI to attract more global capital, it must do more than prove “cheap valuation and low holdings”—it must consistently deliver on revenue, profits, and technological progress.
The key insight behind Goldman’s long position in the China AI value chain is not claiming China AI has caught up to the U.S., but rather exposing a market mispricing: approximately $4 trillion in market cap, ~16% of global AI revenue contribution, yet only ~1.2% allocation in global mutual fund tech exposure.
Whether capital fills this gap will depend on whether policy investment, hardware demand, and corporate profitability continue to materialize.
Source: BlockBeats
Disclaimer: Contains third-party opinions, does not constitute financial advice


DeepSeek Doubles Annual Revenue to $1 Billion Ahead of IPO
10 mins ago
HuggingFace's "AI Duck" Goes Viral, Boosting Chinese Chip Supplier Rockchip
26 days ago
Yushu Surges 629% on First Day of Trading, Humanoid Robots Sell 5,500 Units
08-19
14 Executives Depart, Horizon Unleashes a Robot Legion
08-11
Nokia Snatches AI Optical Chip Race, Stock Soars 52%
08-07
Yushu's 61 Billion IPO: Who Will Make Money?
08-07
AI stocks down 40%-60%, yet NVIDIA's valuation is at a 10-year low
08-06


